

- 1. Key Takeaways
- 2. Table of Contents
- 3. What changed for crypto taxes in 2026: the new broker-reporting rules
- 4. Which crypto transactions are taxable in 2026
- 5. What are the crypto tax rates for 2026?
- 6. How to calculate gains, determine cost basis, and reconcile your 1099-DA
- 7. Which IRS forms you use to report crypto in the 2026 filing season
- 8. What records you need to keep and how to organize them
- 9. Tax planning tactics that still work in 2026
- 10. Global developments and what they mean for U.S. institutional investors
- 11. Critical dates, common mistakes, and penalties to avoid
- 12. Blockchainreporter's analysis: how often broker reports and on-chain records diverge
- 13. Your step-by-step checklist to prepare for the 2026 filing season
- 14. How crypto tax rules affect retirement accounts and employer compensation plans
- 15. Frequently Asked Questions
- 16. Why Blockchainreporter covers crypto tax changes and what to do next
- 17. Sources
- 18. Recommended
Last Updated: November 3, 2026
Crypto taxes in 2026: in the United States, crypto is taxed as property, so selling, swapping or spending it is a taxable disposal that creates a capital gain or loss, while crypto you receive from staking, mining, airdrops or work is ordinary income at its fair market value on the day you receive it. The big change for tax year 2026 is reporting: brokers reported only gross proceeds on Form 1099-DA for 2025 sales, and from January 1, 2026 they must also report cost basis for covered assets, so for those sales the IRS receives both sides of your gain calculation.
Long-term gains on crypto held more than one year are taxed at 0%, 15% or 20% (for 2026, the 0% rate applies up to $49,450 of taxable income for single filers and $98,900 for married couples filing jointly), short-term gains are taxed at ordinary rates of 10% to 37%, and under current law the wash sale rule still does not apply to crypto you hold directly. Returns for tax year 2025 were due April 15, 2026; returns for tax year 2026 are due April 15, 2027. Outside the US, the EU’s DAC8 directive and the UK’s rules under the OECD Crypto-Asset Reporting Framework (CARF) both took effect on January 1, 2026, so crypto platforms are now collecting their users’ 2026 transactions to report them to tax authorities in 2027.
Three things to do before December 31, 2026:
- Reconcile your records. Pull transaction exports from every exchange and wallet before year-end. Your 2026 Form 1099-DA will carry basis only for covered assets, so your own records must cover everything else, including coins bought before 2026 or transferred in from another wallet.
- Choose and document your lot selection. For crypto held at a broker, the 2025 relief that let you identify lots in your own records has ended. In 2026 you need to identify the units with your broker by the time of the sale, or the sale is generally treated as first in, first out (FIFO).
- Set aside liquidity. If you realized gains in 2026, estimate the tax now. Crypto prices can drop after a taxable event, and a later price drop does not reduce the tax owed on a gain you already realized.
Pro Tip: Don’t wait for your 1099-DA to arrive in early 2027 before you start reconciling. By then, exchange APIs may have rate limits or data gaps that make reconstruction painful. Pull your exports quarterly.
Key Takeaways
The most important thing to understand about crypto taxes in 2026 is that the IRS now receives gross proceeds and, for covered assets, cost basis from brokers, making reconciliation between your own records and the broker-issued Form 1099-DA the most critical compliance step this year.
| Point | Details |
|---|---|
| Crypto is property | Selling, swapping or spending crypto is a taxable disposal; staking, mining and airdrop rewards are ordinary income when received. |
| Broker basis reporting is live | Form 1099-DA reports gross proceeds for sales from January 1, 2025 and adds cost basis for covered assets, generally those acquired from January 1, 2026 in the same broker account. |
| 2026 capital gains brackets | 0% up to $49,450 (single) or $98,900 (joint) of taxable income, 15% up to $545,500 or $613,700, and 20% above that. |
| Wash sales | The wash sale rule does not apply to crypto held directly under current law; a House bill advanced on September 16, 2026 would change that but is not law. |
| Deadlines | 2025 returns were due April 15, 2026; 2026 returns are due April 15, 2027, with a filing extension to October 15, 2027. |
| EU and UK | DAC8 (EU) and CARF (UK) reporting started January 1, 2026; platforms report 2026 data in 2027. |
Table of Contents
- What changed for crypto taxes in 2026: the new broker-reporting rules
- Which crypto transactions are taxable in 2026
- What are the crypto tax rates for 2026?
- How to calculate gains, determine cost basis, and reconcile your 1099-DA
- Which IRS forms you use to report crypto in the 2026 filing season
- What records you need to keep and how to organize them
- Tax planning tactics that still work in 2026
- Global developments and what they mean for U.S. institutional investors
- Critical dates, common mistakes, and penalties to avoid
- Blockchainreporter’s analysis: how often broker reports and on-chain records diverge
- Your step-by-step checklist to prepare for the 2026 filing season
- How crypto tax rules affect retirement accounts and employer compensation plans
- Frequently Asked Questions
- Why Blockchainreporter covers crypto tax changes and what to do next
- Sources
What changed for crypto taxes in 2026: the new broker-reporting rules
The 2026 tax year marks a genuine shift in IRS enforcement capability, not just a rule update on paper. Here is the timeline, according to the IRS digital assets page (reviewed September 2, 2026) and the 2026 Instructions for Form 1099-DA:
| Effective Date | What Brokers Must Report | Applies To |
|---|---|---|
| January 1, 2025 | Gross proceeds from digital asset sales on Form 1099-DA | Sales effected by custodial brokers on or after January 1, 2025 (first forms sent in early 2026) |
| January 1, 2026 | Cost basis, in addition to gross proceeds | Certain transactions effected on or after January 1, 2026, mainly covered assets acquired after 2025 and held in the same broker account until the sale (forms sent in early 2027) |
| 2025 and 2026 | Transitional relief | No penalties on brokers for 2025 Forms 1099-DA filed in good faith; backup withholding relief for all 2025 and 2026 transactions (Notices 2024-56 and 2025-33) |
For tax year 2025, the first Forms 1099-DA, sent in early 2026, showed gross proceeds only. The forms arriving in early 2027 for tax year 2026 will be the first to carry both proceeds and basis for covered assets.
What counts as a “covered” asset on Form 1099-DA?
Under the 2026 instructions, a digital asset is covered when it was acquired after 2025 for cash or other property and held in a custodial account until the broker sells it. Every digital asset acquired before 2026 is noncovered, and so are coins you transfer in from another wallet or exchange. The final broker rules also “do not include reporting requirements for brokers commonly known as decentralized or non-custodial brokers,” according to the IRS, so swaps on a decentralized exchange from your own wallet are not reported on Form 1099-DA, but they are still taxable.
A few important caveats on the transition:
- Pre-2026 acquisitions: Brokers are not required to report cost basis for assets acquired before January 1, 2026. You are still responsible for tracking and documenting that basis yourself.
- Transferred-in coins: The 1099-DA instructions say brokers may use acquisition information you provide only to select lots, not to report basis or acquisition dates. Expect blank basis boxes for these sales.
- Staking and small items: Staking rewards are not reported on Form 1099-DA, and brokers do not have to report item by item certain small amounts, such as qualifying stablecoin sales of $10,000 or less and specified NFT sales of $600 or less a year. You still owe tax on them.
- Backup withholding: Relief covers all 2025 and 2026 transactions. For 2027, the relief continues only for certain customers, such as those whose name and taxpayer identification number (TIN) match IRS records, so check that the TIN on file with every exchange is correct now.
The practical consequence is straightforward: the IRS now has a data-matching infrastructure for crypto comparable to what it has had for stock sales for decades. Reporting gaps that went unnoticed before 2025 are increasingly visible.
Which crypto transactions are taxable in 2026
The IRS treats cryptocurrency as property for federal income tax purposes (Notice 2014-21). That one rule drives almost every taxability question you will face.
Taxable events:
- Selling crypto for U.S. dollars or any other fiat currency
- Swapping one cryptocurrency for another (for example, trading ETH for SOL)
- Spending crypto to buy goods or services
- Receiving crypto as payment for work or services (ordinary income at fair market value on receipt)
- Staking rewards received (ordinary income at fair market value when you gain dominion and control, under Revenue Ruling 2023-14; the IRS also cites Tax Court Memo 2026-46, “Cryptocurrency staking rewards are income”)
- Mining income (ordinary income for hobbyists; self-employment income for miners operating as a business)
- Airdrops of new tokens after a hard fork, once you have dominion and control over them (Revenue Ruling 2019-24)
- Selling an NFT at a gain (some NFTs can be taxed as collectibles under Notice 2023-27; see our guide to NFT taxes)
Non-taxable events:
- Buying crypto with fiat currency and holding it
- Transferring crypto between wallets you own (no change in ownership)
- Giving crypto as a gift (not a taxable sale for the giver; gifts above $19,000 per recipient in 2026 require a gift tax return, and the recipient generally takes over your basis)
- Donating crypto to a qualified charity (no capital gain recognized; you may be able to deduct fair market value)
The IRS says that if you have digital asset transactions, “you must report them whether or not they result in a taxable gain or loss,” and taxpayers must report taxable activity whether or not they receive a payee statement. That last point matters: if your exchange does not issue a 1099-DA for a particular transaction, you still owe the tax.
Three worked examples (hypothetical prices):
Example 1, swap: You bought 1 ETH for $2,000 in 2024. In March 2026, you swap it for SOL when ETH is worth $3,500. You realize a $1,500 capital gain. Because you held ETH more than one year, it qualifies for long-term rates.
Example 2, staking income: You receive 0.5 ETH in staking rewards in June 2026 when ETH trades at $3,200. You recognize $1,600 of ordinary income on the date of receipt. Your basis in those 0.5 ETH is $1,600 for any future sale.
Example 3, spending crypto: You pay for a $500 laptop using Bitcoin you bought for $200. You recognize a $300 capital gain at the time of purchase.
What are the crypto tax rates for 2026?
Crypto gains are taxed at capital gains rates, and the rate depends on how long you held the asset. Under IRS Topic 409, crypto held more than one year produces a long-term gain taxed at 0%, 15% or 20%; crypto held one year or less produces a short-term gain taxed as ordinary income at 10% to 37%. Crypto income such as staking rewards is ordinary income, whatever the holding period.
2026 long-term capital gains brackets (taxable income, Revenue Procedure 2025-32):
| Filing status | 0% rate up to | 15% rate up to | 20% rate above |
|---|---|---|---|
| Single | $49,450 | $545,500 | $545,500 |
| Married filing jointly | $98,900 | $613,700 | $613,700 |
| Head of household | $66,200 | $579,600 | $579,600 |
| Married filing separately | $49,450 | $306,850 | $306,850 |
What changed since 2025: the thresholds rose with inflation. For tax year 2025, the 0% rate applied to single filers with taxable income up to $48,350 and the 15% rate up to $533,400 (IRS Topic 409).
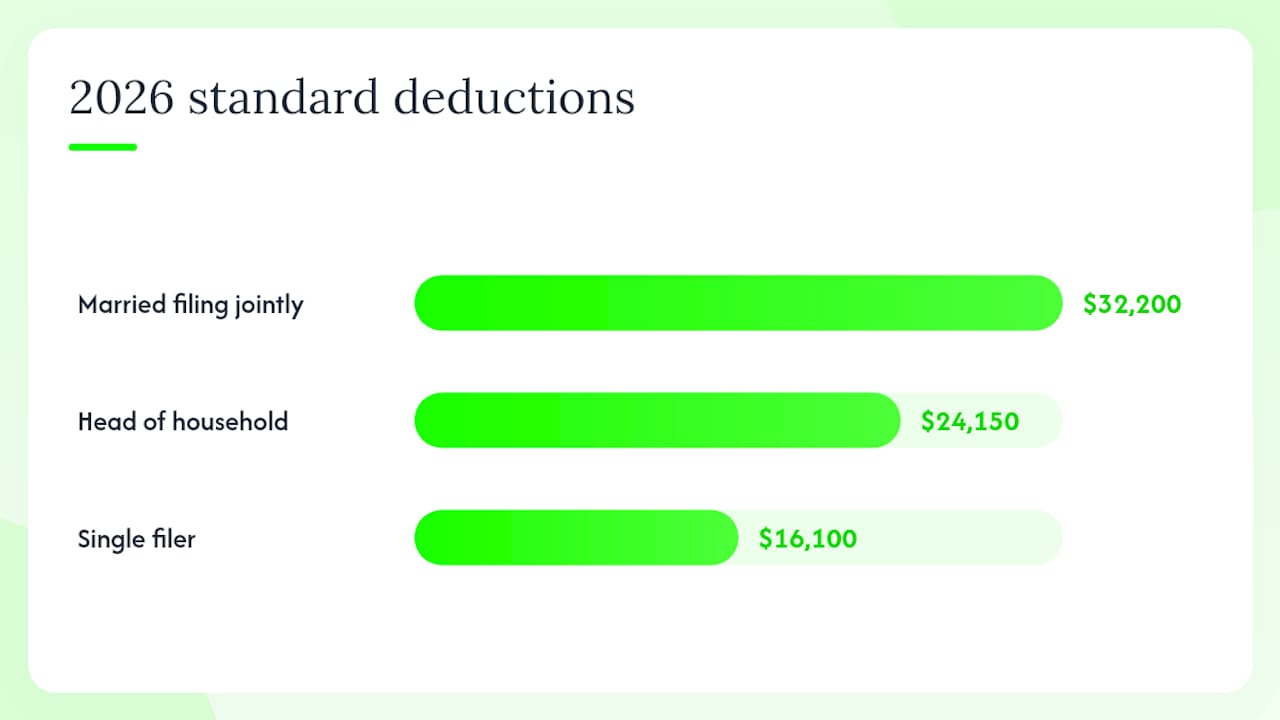
Ordinary income rates for 2026: short-term gains and crypto income are taxed at the regular brackets, from 10% on the first $12,400 of taxable income for single filers ($24,800 for joint filers) to 37% above $640,600 for single filers ($768,700 for joint filers), according to Revenue Procedure 2025-32. The 2026 standard deduction is $16,100 for single filers, $32,200 for married couples filing jointly and $24,150 for heads of household.
Other rules that change the bill:
- Net investment income tax: a 3.8% surtax can apply to investment income, including crypto gains, when modified adjusted gross income exceeds $200,000 (single) or $250,000 (married filing jointly).
- Collectibles: gains on collectibles are taxed at up to 28%, and the IRS has said some NFTs can be treated as collectibles (Notice 2023-27).
- Capital losses: net capital losses offset gains, and up to $3,000 a year ($1,500 if married filing separately) can offset other income; the rest carries forward to later years.
How to calculate gains, determine cost basis, and reconcile your 1099-DA
Reconcile broker gross proceeds to your wallet-by-wallet cost basis, using specific identification where you have made it in time. That is the answer. Everything else is the workflow.
Sample calculation (hypothetical):
| Step | Amount |
|---|---|
| Buy 0.5 BTC for $30,000 plus a $60 trading fee | Cost basis: $30,060 |
| Sell the 0.5 BTC 14 months later for $40,000 minus an $80 fee | Amount realized: $39,920 |
| Gain ($39,920 minus $30,060) | $9,860 long-term capital gain |
The fee paid to acquire an asset increases your basis; the fee paid to sell it reduces your proceeds. Both reduce your taxable gain, so capturing every fee matters.
Wallet-by-wallet basis is the rule. Since January 1, 2025, basis has to be tracked separately for each wallet or account. Revenue Procedure 2024-28 gave taxpayers a safe harbor to allocate their remaining basis to the units held in each wallet or account as of January 1, 2025.
Step-by-step reconciliation workflow:
- Gather exports. Download complete transaction histories from every exchange (CSV or API export) and every wallet you own.
- Match wallet-by-wallet. Organize transactions by the wallet or account where each asset was held. Basis is tracked at the wallet or account level, not across your whole portfolio.
- Trace transfers. Identify every transfer between your own wallets and label them as non-taxable. Missing transfer records are a leading cause of phantom gains on broker reports.
- Adjust for fees. Add acquisition fees to basis; subtract disposition fees from proceeds. Include gas fees for on-chain transactions.
- Document your lot identification. Notice 2025-07 let taxpayers identify broker-held units in their own books and records only for 2025. For sales after December 31, 2025, identify the lot with your broker no later than the time of the sale; without an identification, the 1099-DA instructions say you generally must report the sale of the earliest units first.
- Cross-reference 1099-DA. Compare the gross proceeds on your 1099-DA to your own records. Discrepancies for pre-2026 acquisitions and transferred-in coins are common because brokers show missing basis for noncovered assets.
Pro Tip: A blockchain explorer lets you pull on-chain timestamps and transaction hashes directly, which serve as audit-grade evidence for fair market value at the time of each transaction. Save those records alongside your exchange exports.
Full transaction reconstruction and a consistent cost-basis method are the practical compliance barriers in 2026, not the arithmetic itself. The IRS matching system can flag proceeds that do not align with reported gains, so the reconciliation step is where most audit risk lives.
For institutional investors and high-volume traders, full-service crypto reconciliation can help tie exchange data, wallet activity, cost basis, and transaction records together before filing.
Which IRS forms you use to report crypto in the 2026 filing season
Every crypto transaction flows through a specific form. Here is the mapping:
- Form 1040, digital asset question: All taxpayers must answer “yes” or “no” to the digital asset question on the front page of Form 1040. Answer “yes” if at any time during the year you received digital assets as a reward, award or payment, or sold, exchanged or otherwise disposed of a digital asset.
- Form 1099-DA: The statement your broker sends you and the IRS. For 2025 it showed gross proceeds; for 2026 it adds cost basis for covered assets.
- Form 8949: Report each individual capital gain or loss transaction here. Each row corresponds to one disposal. Transactions from a 1099-DA flow to Form 8949 with the broker’s reported proceeds and basis, plus your own basis where the broker left it blank.
- Schedule D: Aggregates your short-term and long-term totals from Form 8949 and feeds into your overall tax calculation on Form 1040.
- Schedule 1 (Additional Income): Staking rewards, airdrop income, and other crypto income that is not self-employment income go here. The IRS says to use Schedule 1 “to report income from forks, staking, mining, etc.”
- Schedule C: If you mine crypto as a business or receive crypto as self-employment income, report gross income and deductible expenses on Schedule C. Self-employment tax applies.
- Form 1099-NEC: For payments in 2026, a business generally issues a 1099-NEC when it pays you $2,000 or more for services, up from $600 for 2025, according to the IRS instructions for Forms 1099-MISC and 1099-NEC. Crypto paid for services is ordinary income whether or not you receive the form.
- FinCEN Form 114 (FBAR): FinCEN Notice 2020-2 says the FBAR rules “do not define a foreign account holding virtual currency as a type of reportable account,” unless the account also holds other reportable assets such as cash. FinCEN has said it intends to change this, so check the current rule before each filing season.
- Form 8938 (FATCA): Higher thresholds apply, and U.S. taxpayers with significant foreign financial assets, potentially including foreign exchange accounts, may need to file.
- Form 709: Gifts of crypto above $19,000 to one person in 2026 require a gift tax return, even when no gift tax is due.
Three common filing scenarios:
- Employee paid partly in Bitcoin: The employer reports the fair market value of the Bitcoin on your W-2 as wages. You pay ordinary income tax and payroll taxes on that amount. Your basis in the Bitcoin equals the value reported as income. Any later sale triggers a capital gain or loss.
- Staking income only: You receive staking rewards throughout 2026. Each reward is ordinary income at fair market value on receipt, reported on Schedule 1. When you later sell the staked tokens, the gain or loss is capital and goes on Form 8949.
- Active trader on a centralized exchange: Your exchange issues a 1099-DA with gross proceeds for each sale and basis for covered assets. You import those transactions into Form 8949, add your own basis for noncovered lots, and aggregate short-term and long-term totals on Schedule D.
What records you need to keep and how to organize them
The IRS generally recommends keeping tax records for three years after you file, six years if you leave out more than 25% of your gross income, and records about property until the limitations period expires for the year you sell it. For crypto, that means keeping purchase records for as long as you hold a coin and for years after you sell it, because a blank basis box on a 1099-DA is not proof of anything: you must be able to support the basis you report.
Documents and data to retain:
- Complete transaction exports from every exchange (CSV and API format)
- Wallet addresses associated with each account you own
- Transfer records between your own wallets, with timestamps and transaction hashes
- Purchase receipts or confirmation emails showing acquisition price and date
- Fee records for every transaction (acquisition, disposal, gas)
- Staking, mining, and airdrop records with fair market value on the date of receipt
- Lot identification records (which lot you designated for each sale, and when you told your broker)
- Your Revenue Procedure 2024-28 basis allocation as of January 1, 2025
- Exchange account statements and year-end summaries
- 1099-DA forms received from brokers
What to look for in crypto tax software:
- Wallet-level and account-level lot tracing (not just portfolio-wide)
- Specific identification support with audit-log export
- API imports from major exchanges and wallets
- Reconciliation reports that flag missing basis or unmatched transfers
- Export formats compatible with Form 8949 and tax preparation software
Broker-reported basis is available only for covered assets bought on a platform on or after January 1, 2026. For assets acquired before that date, or moved in from another wallet, your own records remain the only source of truth.
Pro Tip: For institutional investors, recordkeeping goes beyond spreadsheets. You need segregated custody records, internal controls over wallet access, and reconciliation reports that tie on-chain activity to your general ledger. A third-party custodian with audit-ready reporting is worth the cost when the portfolio is large enough.
Privacy considerations also affect recordkeeping for peer-to-peer transactions. Research on financial privacy in digital assets highlights how transaction traceability varies significantly across protocols, which affects how thoroughly you can reconstruct a transfer history.
Tax planning tactics that still work in 2026
The core planning toolkit has not changed, but the 2026 broker-reporting environment makes timing and documentation more important than ever. Sales and swaps must happen by December 31, 2026 to count for tax year 2026.
Planning moves worth considering:
- Tax-loss harvesting. Sell positions with unrealized losses to offset gains realized elsewhere. Under current law the wash sale rule does not apply to crypto held directly, so you can repurchase the same asset immediately, but Congress is considering a change (see below), so document your strategy.
- Hold more than one year. Long-term capital gains rates (0%, 15%, or 20% depending on income) are significantly lower than short-term rates, which are ordinary income rates. Selling one day after the one-year mark instead of one day before can make a material difference.
- Donate appreciated crypto. Donating crypto held more than one year directly to a qualified 501(c)(3) charity generally lets you deduct its fair market value without recognizing the capital gain, if you itemize. The IRS Chief Counsel has said a qualified appraisal is required when you claim more than $5,000 for donated crypto (CCA 202302012).
- Gift crypto strategically. Gifts are not taxable sales for the giver, and gifts up to $19,000 per recipient in 2026 need no gift tax return. The recipient generally takes your basis, so this works best when the recipient is in a lower tax bracket.
- Offset income with deductible mining expenses. If you mine as a business, electricity, hardware depreciation, and facility costs are deductible against mining income on Schedule C.
Does the wash sale rule apply to crypto in 2026?
No, not under current law. The wash sale rule in Section 1091 of the Internal Revenue Code covers “stock or securities,” and the IRS treats crypto as property, so a loss on crypto you hold directly is not disallowed when you buy the same coin back within 30 days. The rule does apply to securities linked to crypto, such as shares of spot bitcoin ETFs and crypto company stocks.
That could change. On September 16, 2026, the House Ways and Means Committee approved the Digital Asset Tax Certainty Act (H.R. 10357) by 38 votes to 5. The bill would extend wash sale rules to digital assets and would exempt network and transaction fees of $10 or less from gain or loss recognition for taxpayers with no more than 5,000 digital asset transactions a year, according to EY’s summary of the markup. As of November 3, 2026, the bill is not law: it still needs a vote of the full House, Senate passage and the President’s signature, and bills not enacted by the end of the current Congress in January 2027 lapse. Read more in our report on the House committee vote.
Liquidity planning is not optional. Crypto prices can fall sharply after you realize a gain. If you sold Bitcoin at $90,000 in January and the price drops to $60,000 by April, you still owe taxes on the January gain. Estimated tax payments for 2026 were due April 15, June 15 and September 15, 2026, and the last one is due January 15, 2027, according to the IRS.
For tax year 2026, the IRS has set the standard deduction at $32,200 for married filing jointly, $16,100 for single filers, and $24,150 for heads of household. These thresholds affect whether itemizing deductions (including charitable contributions of crypto) makes sense for your situation.
Where software falls short: cross-exchange histories, DeFi activity, NFT sales, staking income across multiple protocols and foreign exchange accounts add complexity that most tax software does not handle reliably. Automated tools are accurate for straightforward buy-sell histories; they struggle with bridging transactions, liquidity pool entries and exits, and wrapped-token mechanics.
Global developments and what they mean for U.S. institutional investors
The U.S. broker-reporting expansion is not happening in isolation. The OECD’s Crypto-Asset Reporting Framework (CARF) is being adopted across dozens of jurisdictions, creating a global information-exchange network for crypto transaction data, and the EU and the UK both started collecting data under it on January 1, 2026.
What is DAC8 and what changed in the EU on January 1, 2026?
DAC8 is Council Directive (EU) 2023/2226 of October 17, 2023, the EU’s version of CARF. EU countries had to transpose it by December 31, 2025 and apply it from January 1, 2026, according to the European Commission. Reporting crypto-asset service providers collect information on their users’ acquisitions, disposals and transfers, report it to national tax authorities in the year after the reporting year, and the first exchanges between EU countries, covering 2026, take place by September 30, 2027. The scope builds on the definitions of the Markets in Crypto-Assets regulation (MiCA) and also covers stablecoins, e-money tokens and certain NFTs. DAC8 does not set tax rates: each EU country keeps its own rules for taxing crypto gains.
What changed for UK crypto taxes in 2026?
The UK applies CARF to UK-resident users as well as residents of other CARF countries. UK crypto service providers must collect their users’ details and send HMRC their first report, covering January 1 to December 31, 2026, by May 31, 2027, and HMRC may charge a provider a penalty of up to £300 per user for failures, according to HMRC’s guidance (updated November 2, 2026). The tax itself is unchanged: gains are subject to Capital Gains Tax at 18% within the basic rate band and 24% above it (gov.uk), after the £3,000 annual tax-free allowance. HMRC figures for the year to April 5, 2025 showed 17,600 taxpayers declaring £1.38 billion of crypto gains, as covered in our HMRC report.
Which other countries share crypto tax data under CARF?
Ireland’s Revenue lists, as of June 10, 2026, 48 jurisdictions with first CARF or DAC8 exchanges by 2027 (covering 2026 data), including the UK, Japan, Brazil and EU countries, and 26 more by 2028, including Canada, Australia, Switzerland, Singapore and the United Arab Emirates (Revenue list). The United States is not on that list. The President’s Working Group on Digital Asset Markets recommended in its July 30, 2025 report that Treasury and the IRS consider proposing regulations to implement CARF. For the wider legal picture by country, see our global crypto regulation tracker.
The EU’s MiCA regulation is also reshaping how European counterparties operate. Its transitional periods ended on July 1, 2026, so firms without a MiCA authorization must wind down their EU business, which affects how U.S. institutions interact with EU-based exchanges and custodians.
Institutional risks to address now:
- FATCA and FBAR exposure: Foreign accounts above the applicable thresholds trigger reporting obligations. A foreign account holding only crypto is not currently reportable on the FBAR, but one that also holds cash or securities can be, and Form 8938 has its own rules.
- Cross-border data sharing: Even exchanges outside U.S. broker rules now report to their home tax authorities under CARF or DAC8, and U.S. persons with accounts abroad should expect those records to exist.
- Custodial reconciliation: When assets move between custodians, cost-basis records must transfer with them. Coins moved in are noncovered at the receiving broker, so gaps in custody chains create basis documentation problems that compound over time.
- Stablecoin treatment at scale: Large stablecoin positions used for treasury management may generate taxable events on redemption or swap, depending on the structure. The GENIUS Act regulates stablecoin issuers but does not change how stablecoin transactions are taxed.
- DeFi and NFT activity: The IRS has not issued comprehensive guidance on liquidity pool entries, yield farming, or NFT royalties. Until it does, conservative treatment (recognize income at fair market value on receipt; recognize gain or loss on disposal) is the defensible approach. Our guide to DeFi explains the mechanics behind these transactions.
Practical steps for U.S. institutions:
Coordinate tax and treasury teams so that trading decisions account for tax consequences in real time, not at year-end. Document custody chains with timestamped records at every transfer point. Run data-matching controls between your general ledger, custodian reports, and on-chain records at least quarterly. For complex DeFi positions, review the on-chain history with blockchain forensics tools before filing.
Critical dates, common mistakes, and penalties to avoid
When are crypto taxes due for 2025 and 2026?
Crypto is reported on your regular federal return, so the deadlines are the same as for any other income. Returns for tax year 2025 were due April 15, 2026 (October 15, 2026 with an extension), and that deadline has passed; late 2025 returns should be filed as soon as possible to limit penalties. Returns for tax year 2026, the first year with broker-reported basis, are due April 15, 2027.
Key dates for the 2026 tax year:
- January 1, 2026: Cost-basis reporting begins for covered digital assets acquired on this date or later; DAC8 and UK CARF data collection begins.
- Quarterly estimated payments: April 15, June 15 and September 15, 2026, and January 15, 2027, for taxpayers with significant crypto income.
- December 31, 2026: Last day for sales and loss harvesting to count in tax year 2026.
- January 31, 2027: UK online Self Assessment deadline for the 2025 to 2026 tax year.
- Early 2027: Brokers send Forms 1099-DA for 2026 activity, with basis for covered assets.
- April 15, 2027: Standard filing and payment deadline for 2026 tax-year returns (Form 1040).
- May 31, 2027: First UK CARF reports due to HMRC.
- September 30, 2027: First DAC8 exchanges between EU tax authorities.
- October 15, 2027: Extended filing deadline (requires Form 4868 filed by April 15). An extension gives you more time to file, not more time to pay. Taxes owed are still due April 15.
Common mistakes that trigger problems:
- Failing to reconcile 1099-DA gross proceeds against your own records before filing. If the IRS receives a 1099-DA showing $50,000 in proceeds and your return shows $30,000, expect a notice.
- Misclassifying staking or airdrop income as capital gains instead of ordinary income. The tax rate difference is significant.
- Calculating basis across all wallets combined instead of wallet by wallet, as required since January 1, 2025.
- Assuming a sale is FIFO-proof because you picked a lot in a spreadsheet: for broker-held crypto in 2026, the identification has to be made with the broker by the time of the sale.
- Treating wallet-to-wallet transfers as taxable disposals (they are not, but you must document them as transfers).
- Missing FBAR or Form 8938 filing requirements for foreign accounts.
Penalties: Accuracy-related penalties run 20% of the underpayment, and civil fraud penalties 75%. The failure-to-file penalty is 5% of the unpaid tax for each month or part of a month, up to 25%, and for returns due after December 31, 2025 that are more than 60 days late, the minimum is $525 or 100% of the tax due, whichever is less, according to the IRS. The failure-to-pay penalty adds 0.5% a month. If you discover an error after filing, an amended return (Form 1040-X) reduces exposure and demonstrates good faith. Voluntary disclosure before IRS contact is always better than waiting.
Blockchainreporter’s analysis: how often broker reports and on-chain records diverge
Reconciliation is where most investors are surprised. Blockchainreporter’s review of the 2026 Form 1099-DA rules points to three categories where broker reports will predictably diverge from on-chain records.
| Mismatch Category | Primary Cause | Typical Impact |
|---|---|---|
| Missing cost basis | Asset acquired before January 1, 2026, or transferred in from another wallet (noncovered) | Basis box left blank; investor must supply and support the basis |
| Transfer mislabeling | Wallet-to-wallet move recorded as a sale | Phantom gain reported; needs correction on Form 8949 |
| Fee misallocation | Gas or network fees excluded from basis | Basis understated; gain overstated |
The missing-basis problem is the most common and the most consequential. Because broker basis reporting applies only to covered assets acquired on or after January 1, 2026, most existing holdings will appear on 1099-DA forms with no basis entry. A blank box does not mean zero basis, but if you cannot document what you paid, you cannot support a lower gain.
Transfer mislabeling happens when an outbound transfer to a personal wallet is recorded as a sale, generating a 1099-DA entry with proceeds but no corresponding purchase on the receiving side. Without transfer documentation, the investor appears to have sold an asset they still hold.
Fee misallocation is smaller per transaction but compounds across active traders. Gas fees paid to execute a swap, for example, are part of the cost of acquiring the new asset. Excluding them understates basis across hundreds of transactions.
Three recommendations based on these patterns:
- Reconcile early, not at tax time. Pull your exchange exports and on-chain records now and flag discrepancies while the data is fresh and exchange support is reachable.
- Preserve transfer evidence. For every wallet-to-wallet transfer, save the transaction hash, the sending and receiving addresses, and a note confirming both wallets belong to you.
- Flag noncovered lots. Mark every lot acquired before 2026 or transferred in, with its date, cost and wallet, so you can fill in blank basis boxes on Form 8949 quickly.
Your step-by-step checklist to prepare for the 2026 filing season
Follow these steps in order. Each one builds on the last.
- Pull all transaction exports from every exchange and wallet you used in 2026. Download CSV files and save API exports. (Time: short, 1 to 2 hours)
- Organize by wallet and account. Create a folder or spreadsheet tab for each exchange account and self-custody wallet. (Time: short, 1 to 2 hours)
- Identify and label all transfers. Flag every transaction where you moved assets between your own wallets. Document the transaction hash and both addresses. (Time: medium, 2 to 4 hours depending on volume)
- Calculate gains and losses per lot. Use FIFO, or the specific lots you identified with your broker by the time of each sale, and calculate the gain or loss on each disposal. (Time: medium to long, depending on transaction count)
- Reconcile against 1099-DA. When your 1099-DA arrives in early 2027, compare the gross proceeds and any reported basis line by line against your own records. Flag any discrepancy before filing. (Time: medium, 1 to 3 hours)
- Classify income correctly. Separate capital gains from ordinary income (staking rewards, mining, airdrops, wages paid in crypto). Each category goes to a different form. (Time: short, 30 to 60 minutes)
- Estimate your tax liability. Add up short-term gains (taxed as ordinary income) and long-term gains (taxed at 0%, 15% or 20%). Apply your marginal rate to get a rough liability figure. (Time: short, 30 to 60 minutes)
- Set aside funds for taxes owed. If you have not been making quarterly estimated payments, set aside the estimated liability in a separate account now; the last 2026 installment is due January 15, 2027. (Time: immediate)
- Prepare Form 8949 and Schedule D. Enter each capital transaction on Form 8949. Aggregate totals flow to Schedule D. (Time: long, varies by transaction volume)
- Back up all records. Store copies of exports, transaction hashes, lot identifications and 1099-DA forms in at least two locations (cloud and local). Keep them for as long as you hold the assets and for years after you sell them. (Time: short, 30 minutes)
How crypto tax rules affect retirement accounts and employer compensation plans
Crypto held inside a traditional IRA or Roth IRA is not subject to capital gains tax on trades made within the account. Gains compound tax-deferred (traditional) or tax-free (qualified Roth distributions), and the tax event occurs only on distribution. That makes retirement accounts one of the most tax-efficient vehicles for crypto exposure, particularly for long-term holders who would otherwise face short-term rates on active trading.
The practical limitation is access. Most traditional IRA custodians do not support direct crypto holdings. Self-directed IRAs can hold crypto, but they require a qualified custodian and come with higher fees and compliance complexity. Prohibited transaction rules under IRC Section 4975 apply strictly: using IRA-held crypto for personal benefit, or transacting with disqualified persons, can disqualify the entire account and trigger immediate taxation plus penalties.
Employer compensation plans are a different story. If your employer pays you in Bitcoin or another digital asset, that compensation is ordinary income at the fair market value on the date you receive it, reported on your W-2. Payroll taxes apply. Your basis in the received crypto equals the value reported as income, so a later sale triggers only the gain above that basis.
Some employers offer crypto as a 401(k) investment option, though adoption remains limited. The Department of Labor rescinded its 2022 guidance cautioning plan fiduciaries against crypto on May 28, 2025, and an August 2025 executive order directed the department to revisit its guidance on alternative assets, including digital assets, in 401(k) plans. If your plan offers crypto funds, the same tax-deferred treatment applies as with any other 401(k) investment: no tax on gains inside the plan, ordinary income tax on distributions.
Trades inside a qualified retirement account are not reported as taxable sales; distributions are reported on Form 1099-R. Keep records of the fair market value at the time of any distribution involving crypto assets.
Frequently Asked Questions
What are the crypto tax rules for 2026?
In the United States, crypto is property. Selling, swapping or spending it creates a capital gain or loss, and staking, mining, airdrop and payment income is ordinary income at fair market value when received. New for 2026, brokers add cost basis for covered assets to Form 1099-DA, which already reported gross proceeds for 2025 sales. The EU and UK also began collecting crypto tax data.
Do I pay tax on crypto if I don’t sell?
Holding crypto is not a taxable event, and neither is moving it between your own wallets or buying it with dollars. Tax applies when you sell, swap or spend crypto, or when you receive it as income, for example as staking rewards, mining rewards, airdrops or payment for work. Unrealized gains on coins you still hold are not taxed in 2026.
What is Form 1099-DA and what does it show for 2025 and 2026?
Form 1099-DA is the statement crypto brokers send to customers and the IRS. For 2025 sales, sent in early 2026, it showed gross proceeds only. For 2026 sales, sent in early 2027, it also shows cost basis for covered assets, generally those acquired from January 1, 2026 and held in the same broker account. Older and transferred-in coins have no reported basis.
What are the capital gains tax rates on crypto in 2026?
Crypto held more than one year is taxed at 0%, 15% or 20%. For 2026, the 0% rate applies up to $49,450 of taxable income for single filers and $98,900 for joint filers, and 20% applies above $545,500 and $613,700. Crypto held one year or less is taxed at ordinary rates from 10% to 37%.
Does the wash sale rule apply to crypto in 2026?
Not under current law. The wash sale rule covers stock or securities, and the IRS treats crypto as property, so you can sell crypto at a loss and buy it back within 30 days. The rule does apply to crypto ETF shares. A House bill approved by the Ways and Means Committee in September 2026 would extend wash sale rules to crypto.
How are staking rewards taxed in 2026?
Staking rewards are ordinary income at their fair market value when you gain control of them, under IRS Revenue Ruling 2023-14, and the IRS also points to a 2026 Tax Court memo holding that staking rewards are income. Report them on Schedule 1. That value becomes your basis, so a later sale creates a separate capital gain or loss.
When is the deadline to file crypto taxes?
Crypto goes on your regular federal return. Returns for tax year 2025 were due April 15, 2026, or October 15, 2026 with an extension, so both dates have passed. Returns for tax year 2026 are due April 15, 2027, or October 15, 2027 with an extension, although any tax owed is still due on April 15, 2027.
What changed for crypto taxes since 2025?
Gross proceeds reporting on Form 1099-DA began with 2025 sales, and cost basis reporting began on January 1, 2026. Wallet-by-wallet basis tracking became mandatory in 2025, the 2025 relief for identifying lots in your own records ended, capital gains brackets rose with inflation, and the Form 1099-NEC threshold rose from $600 to $2,000 for 2026 payments.
What is DAC8 and does it affect EU crypto users?
DAC8 is the EU directive that applies the OECD Crypto-Asset Reporting Framework in all member states from January 1, 2026. Crypto service providers collect users’ tax details and transaction data for 2026, report them to national tax authorities, and EU countries exchange the first data by September 30, 2027. DAC8 does not change tax rates, which each country sets.
How does CARF affect UK crypto users in 2026?
UK crypto platforms have collected users’ details and transactions since January 1, 2026 and must send HMRC their first report, covering 2026, by May 31, 2027. That covers UK residents as well as users in other CARF countries. The tax rules themselves are unchanged: Capital Gains Tax at 18% or 24% after a £3,000 annual allowance.
Do I have to report crypto if my exchange does not send a 1099-DA?
Yes. The IRS says digital asset transactions must be reported whether or not they result in a gain or loss, and whether or not you receive a payee statement. Decentralized exchanges, self-custody wallets, foreign platforms and small items below reporting thresholds often produce no 1099-DA, but the tax is still owed and the sales still go on Form 8949.
Why Blockchainreporter covers crypto tax changes and what to do next
Blockchainreporter tracks regulatory developments because accurate tax reporting is foundational to the long-term health of the crypto market. Investors who misreport, even unintentionally, face penalties that erode the gains they worked to build. The 2026 broker-reporting changes are the most significant shift in crypto tax enforcement since the IRS first classified digital assets as property in Notice 2014-21, and with DAC8 and CARF the same shift is under way in Europe and beyond.
The guidance in this article reflects IRS, HMRC and EU rules as of November 3, 2026. For ongoing coverage of regulatory changes, market developments, and crypto news, visit Blockchainreporter.

This article is general information, not tax advice; tax rules vary by country and personal situation, so check with a qualified tax professional before acting on anything here.
Sources
The sources below are the primary and official references used throughout this article, checked on November 3, 2026. Bookmark them and check for updates, since tax guidance pages are revised as new rules take effect.
- IRS: Digital assets
- IRS: Instructions for Form 1099-DA (2026)
- IRS: Revenue Procedure 2025-32 (2026 inflation adjustments)
- IRS: Notice 2025-07 (lot identification relief for 2025)
- IRS: Topic 409, Capital gains and losses
- IRS: Estimated tax due dates
- IRS: Failure to file penalty
- IRS: Instructions for Forms 1099-MISC and 1099-NEC
- FinCEN Notice 2020-2: Virtual currency reporting on the FBAR
- European Commission: DAC8
- HMRC: Reporting cryptoasset user and transaction data
- GOV.UK: Capital Gains Tax rates
- Irish Revenue: CARF and DAC8 reportable jurisdictions
When a third-party summary conflicts with an official document, the official document controls.
Recommended